
Understanding Section 69A Additions In Tax Law
Tax disputes often arise when authorities question the source of valuable assets discovered during assessments. Section 69A of the income tax framework deals with unexplained money, bullion, jewellery, or other valuable articles. When a taxpayer cannot satisfactorily explain the ownership or the source of acquisition for such items, tax authorities frequently treat the estimated value as undisclosed income. This can lead to substantial financial additions and prolonged legal battles for individuals and joint families alike.
The Case Context Before ITAT Ranchi
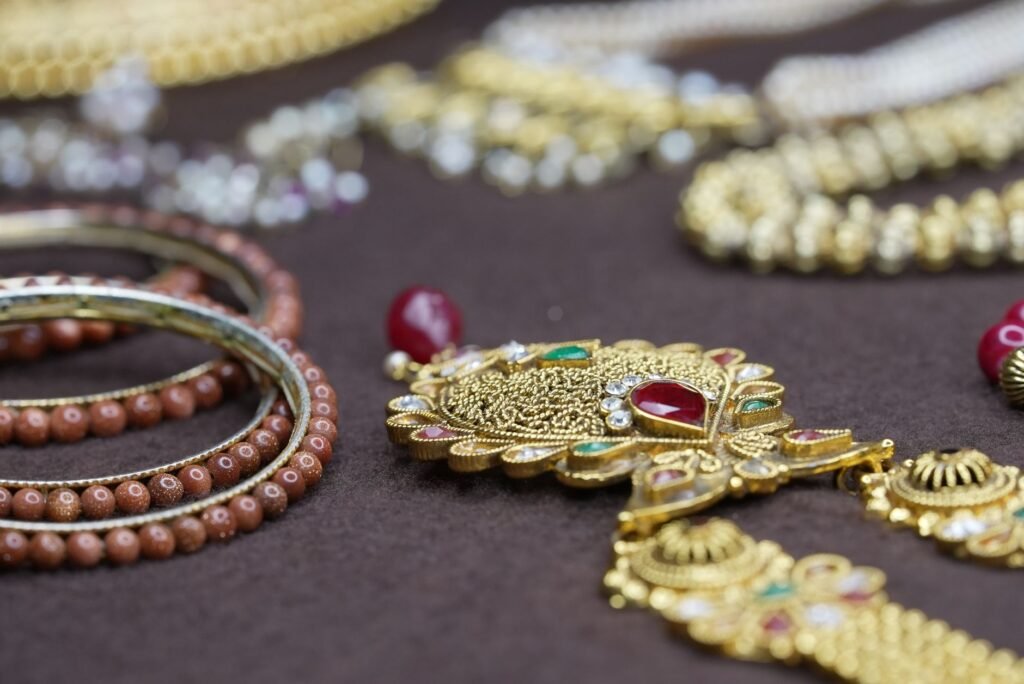
A notable legal development recently emerged from the Ranchi bench of the Income Tax Appellate Tribunal. The tribunal addressed a major dispute involving family jewellery and bullion valued at Rs 27.54 lakh. Tax authorities had initially treated this valuable inventory as unexplained under Section 69A, leading to significant additions to the taxpayer’s assessed income. The central issue revolved around whether the traditional family holdings and previously declared assets were sufficient to justify the possession of the gold and bullion.
Role Of VDIS Declarations And Invoices
During the appellate proceedings, the legal representatives presented comprehensive documentation to substantiate the legitimacy of the assets. The submission included formal purchase invoices that clearly traced the acquisition of portions of the jewellery and bullion. Furthermore, the defense heavily relied on declarations made under the Voluntary Disclosure of Income Scheme, commonly known as VDIS. These historical disclosures established that a significant portion of the valuable items had already been declared to the authorities in the past, thereby providing a legal and transparent origin for the family assets.
Tribunal Analysis And Judicial Reasoning
Upon reviewing the evidence, the tribunal carefully evaluated the credibility of the invoices and the historical VDIS declarations. The judicial members noted that the tax authorities had failed to dismantle the documentary proof provided by the taxpayer. In joint family setups, holding traditional gold and inherited bullion is a common cultural practice. When supported by verifiable paperwork and formal disclosures, the presumption of unexplained income under Section 69A loses its legal standing.
Relief Granted To The Taxpayer
In light of the substantiated facts and acceptable explanations, the tribunal ruled in favor of the taxpayer. The bench ordered the complete deletion of the Rs 27.54 lakh addition that had been levied under Section 69A. This decision provides a crucial precedent for cases where joint family gold, supported by valid purchase records and past scheme declarations, faces arbitrary scrutiny by assessing officers.
Key Takeaways For Property And Asset Holders
This ruling underscores the vital importance of maintaining meticulous records for high-value assets such as gold, silver, and bullion. Taxpayers must retain authentic purchase bills, valuation reports, and documents related to historical tax amnesty or disclosure schemes. By establishing a clear paper trail, families can successfully defend their legitimate holdings against unwarranted tax additions and secure favorable outcomes in appellate tribunals.