
The regulatory landscape surrounding defense procurement and taxation has seen a notable development following a recent pronouncement by the Gujarat Authority for Advance Ruling. This administrative decision addresses the tax liabilities associated with major defense manufacturing initiatives in the region and clarifies the statutory obligations for entities involved in large-scale aerospace projects with national defense authorities.
Background of the C-295 Aircraft Project
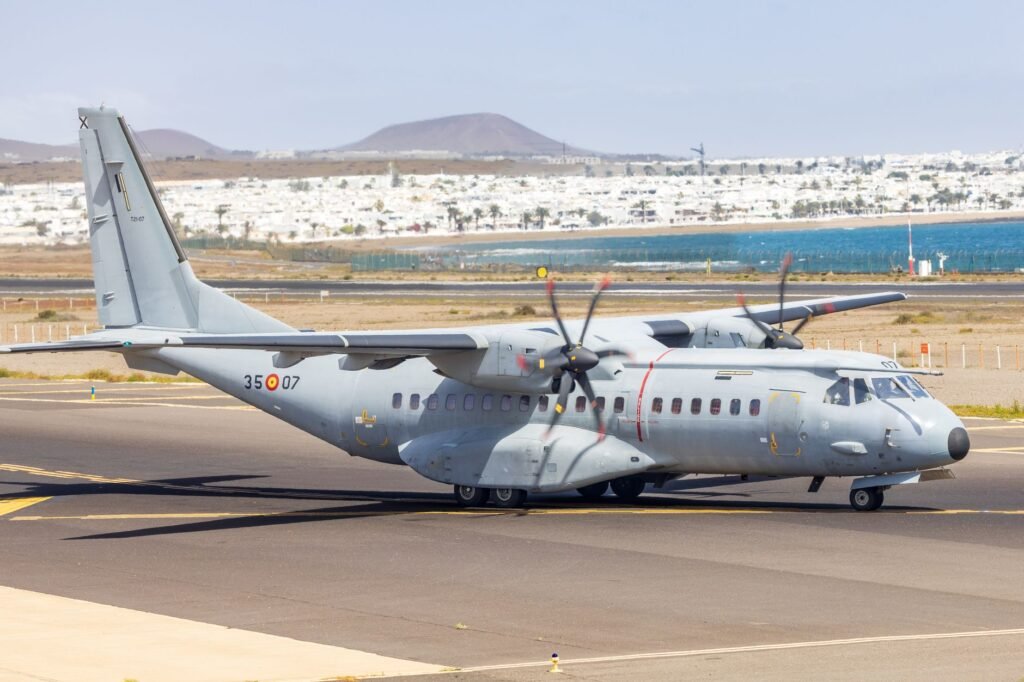
The case centers around the high-profile defense initiative involving the procurement of C-295 transport aircraft for the Indian Ministry of Defence. This manufacturing and supply undertaking is designed to bolster the operational capabilities of the national armed forces through modern tactical transport solutions. As part of the execution framework, project offices are established to oversee logistical, technical, and commercial coordination on the ground.
Key Findings of the Gujarat Authority for Advance Ruling
The central issue examined by the authority was whether the transaction pertaining to the delivery of these aircraft falls within the scope of the prevailing tax framework. The ruling concluded that the Airbus Project Office operating within the jurisdiction is indeed accountable for Goods and Services Tax on the supply of the forty C-295 aircraft designated for the Ministry of Defence.
Mandatory Registration Requirements
Beyond determining the applicability of the tax on the aircraft supply, the authority addressed the administrative prerequisites for the project office. The official stance mandates that the entity must secure a formal Goods and Services Tax registration within the state of Gujarat to ensure full compliance with local regulatory norms. This registration ensures that all commercial activities, operational inputs, and subsequent transactions align with statutory mandates.
Implications for Defense Contractors
This decision carries substantial weight for defense contractors and international aerospace firms operating within the country. It reinforces the principle that large-scale defense supply contracts executed through local project offices are subject to domestic indirect taxation unless specific exemptions apply under the law. Stakeholders must carefully evaluate their contractual obligations, supply chain structures, and operational setups to maintain strict adherence to statutory tax requirements.
Conclusion
The clarification provided by the Gujarat Authority for Advance Ruling marks an important milestone in the intersection of defense acquisition and indirect taxation. By establishing clear guidelines on tax applicability and mandatory state-level registration, the ruling brings greater certainty and transparency to major defense projects moving forward.