
Understanding the Recent Legal Dispute
Tax administration often involves complex classification challenges that can persist for years. Recently, the legal framework surrounding indirect taxation faced an important test regarding procedural fairness and the finality of judicial decisions. Businesses operating in regulated sectors frequently encounter compliance hurdles when tax authorities attempt to reopen previously settled matters. A notable judgment by the High Court of Rajasthan has addressed this very issue, offering clarity on how prior rulings impact subsequent administrative actions.
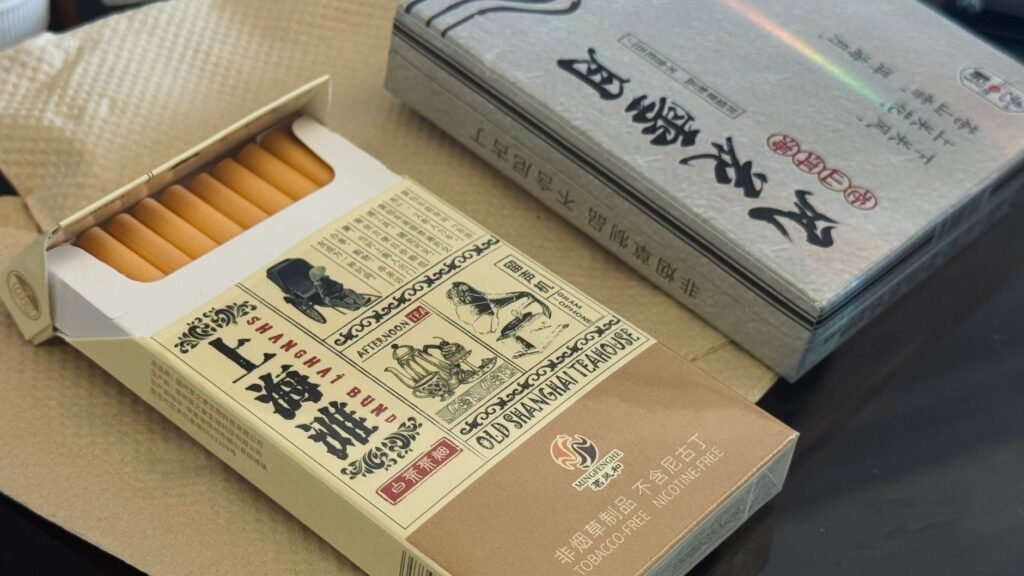
The core of the controversy revolved around the categorization of tobacco products for excise duty purposes. Classification disputes are notoriously intricate, as minor variations in product definitions or manufacturing processes can lead to vastly different tax liabilities. When tax authorities issue notices to reexamine these categories, it creates significant uncertainty for commercial enterprises trying to maintain stable operations and financial planning.
Background of the Classification Controversy
The dispute began when tax officials initiated proceedings regarding how specific tobacco goods should be classified under applicable excise statutes. Such classification dictates the specific rate of duty applied to the merchandise. Businesses rely heavily on statutory definitions and established administrative precedents to calculate their financial obligations accurately. When authorities challenge these established positions, it frequently results in prolonged litigation.
In this particular instance, the legal battle was not entirely new. The core question regarding the precise categorization of the tobacco items in dispute had already been subjected to rigorous legal scrutiny in prior proceedings. A binding judicial determination had previously addressed the merits of the classification controversy, establishing a clear legal precedent between the involved parties.
Filing of the Writ Petition
Despite the existence of a definitive earlier ruling addressing the exact same classification controversy, the tax administration elected to issue a fresh excise notice. This subsequent notice sought to reopen the settled matter, prompting the affected enterprise to seek judicial intervention. Facing what they perceived to be an administrative overreach and harassment through repetitive litigation, the petitioners approached the High Court of Rajasthan.
Through a formal writ petition, the aggrieved party challenged the legality and validity of the repeat excise notice. The central argument rested on the principle of judicial finality and the binding nature of prior adjudications. Allowing tax authorities to issue consecutive notices on identical matters, particularly after a court of competent jurisdiction has already resolved the issue, undermines the rule of law and places an unfair burden on taxpayers.
Key Findings of the High Court
Upon reviewing the arguments presented by both sides, the High Court of Rajasthan delivered a decisive verdict in favor of the petitioner. The judiciary examined whether a repeat notice could legally survive when the underlying controversy had already been conclusively adjudicated. The court firmly established that administrative authorities cannot bypass earlier binding rulings simply by issuing fresh notices on the exact same subject matter.
The bench emphasized that judicial certainty is paramount in tax jurisprudence. Once a court or appellate authority resolves a specific classification dispute, that determination holds binding force. Tax officials are legally bound to respect these precedents rather than initiating repetitive proceedings that challenge settled outcomes. Consequently, the court allowed the writ petition and set aside the repeat excise notice.
Broader Implications for Tax Administration
This judicial outcome carries significant implications for both tax administrators and the business community. For enterprises engaged in manufacturing and trade, the ruling reinforces the protection against arbitrary or repetitive administrative actions. It confirms that businesses do not need to endlessly defend the same classification decisions once a court has validated their position.
For tax authorities, the judgment serves as an important reminder of the limits of administrative power. It underscores the necessity of respecting judicial finality and avoiding the duplication of proceedings on matters that have already reached a legal conclusion. By upholding the sanctity of earlier rulings, the High Court of Rajasthan has reinforced stability and predictability within the indirect tax framework.